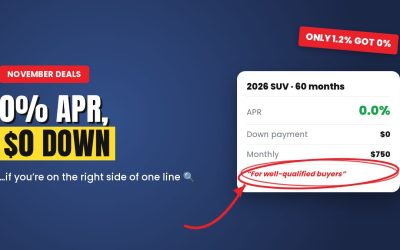
The lowest monthly payment in our guide to buying a car with $0 down in 2026 doesn’t come from a loan. It comes from a lease, and in November 2026 several brands advertise one with nothing due when you sign.
The best example is Hyundai. Its national offer this month is a 2026 Tucson SE for $359 a month for 36 months, $0 due at signing, for well-qualified lessees, through November 30. In October, the same car was advertised at $249 a month with $3,999 due.
Same car, almost the same total
| October | November | |
| Due at signing | $3,999 | $0 |
| Monthly | $249 | $359 |
| 36 months, total | About $12,700–$13,000 | $12,924 |
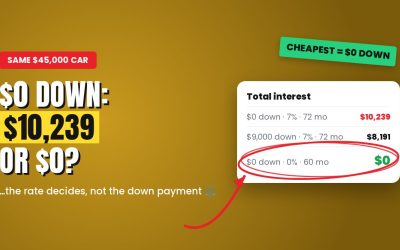
The range on the October deal depends on whether the $3,999 included the first month. Either way, the gap is a few hundred dollars over three years. “$0 due” didn’t make the car cheaper: it moved the down payment into the monthly price. That is how almost every zero-down offer works, lease or loan.
Is that bad? Not necessarily. Keeping $4,000 in your account is worth something, and Edmunds actually advises putting as little down as possible on a lease: if the car is stolen or totaled early, the money you put down is usually lost.
What “$0 due” doesn’t cover
Hyundai’s fine print excludes “registration, tax, title, license, processing or documentation fees, insurance”. Depending on your state, that can still be several hundred dollars on the day you sign. Ask the dealer for the out-the-door amount in writing.
The three numbers that decide a lease
- Money factor. The lease’s interest rate, written as a small decimal. Multiply by 2,400 to compare it with an APR: 0.002 is about 4.8%. Dealers can mark it up, and it is negotiable.
- Mileage. Most leases allow 10,000 to 12,000 miles a year. Ford’s Bronco Sport lease this month, for example, allows 31,500 miles over 36 months and charges $0.20 for every mile above that. 5,000 extra miles is $1,000 at the end.
- Residual value. What the car is expected to be worth at the end. A high residual means a lower payment.
Lease or loan?
Experian found that the average new-car loan payment was $148 a month higher than the average lease payment in the second quarter of 2026. Leasing makes sense if you drive a predictable number of miles and like to change cars every three years.
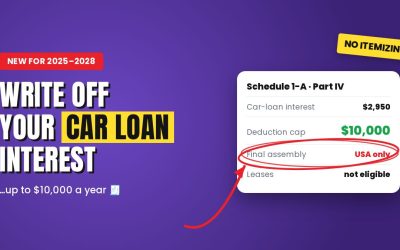
One thing to know: leases do not qualify for the new federal car-loan interest deduction. If your income is under $100,000 and you’re buying an American-assembled car, a loan may come out ahead after taxes. We explain it in the new $10,000 car-loan interest deduction.
Offers, rates and rules are those published by each automaker, lender or agency as of November 2026 and can change at any time; manufacturer offers usually end with the month and vary by region. Approval and your rate depend on your credit. This article is for information only and is not financial or tax advice.