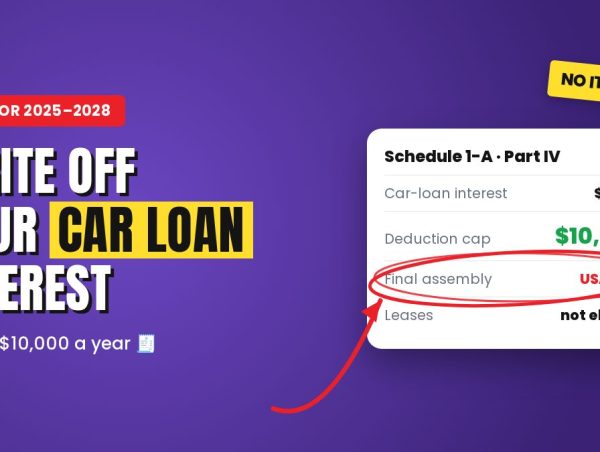
This is the newest piece of our guide to buying a car with $0 down in 2026, and many buyers still don’t know it exists. The 2025 tax law created a deduction for interest on car loans, and the IRS published the final rules in September 2026.
The rules in plain English
- Up to $10,000 a year of interest, per tax return, for tax years 2025 through 2028.
- You don’t need to itemize. It goes on the new Schedule 1-A.
- New vehicles only: car, SUV, minivan, van, pickup or motorcycle, for personal use. Used cars don’t qualify.
- Final assembly in the United States. The brand doesn’t matter: where the car was put together does.
- Loans taken out after December 31, 2024, secured by the car.
- Leases don’t qualify.
The income limit
The deduction shrinks by $200 for every $1,000 of income above $100,000 for single filers or $200,000 for joint filers. It disappears completely at $150,000 and $250,000.
How to check if your car qualifies
Look at the window sticker: it lists the final assembly point. You can also enter the VIN in the free NHTSA VIN Decoder, which shows the plant. The IRS says it will not decide by make and model, so check the exact car you are buying. You will need to write the VIN on your tax return every year you claim the deduction.
What it’s worth
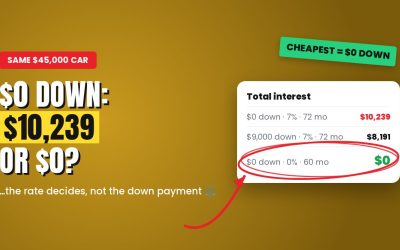
It’s a deduction, not a credit, so it lowers your taxable income. On a $45,000 loan at 7% over 72 months, first-year interest is about $2,950. In the 22% tax bracket, that is roughly $650 back for the first year, and less every year after as the balance falls.
The zero-down detail that shrinks it
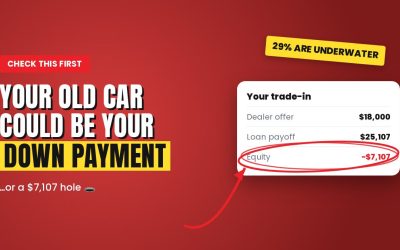
Taxes, fees, service plans and extended warranties financed with the car count as part of the loan. But negative equity rolled in from a trade-in does not. If you owe $7,000 more on your old car than it’s worth and add it to the new loan, the interest on that part is not deductible, and you have to split it out.
That is one more reason to fix negative equity before buying. We show how in using your trade-in as the down payment.
The form your lender sends
Lenders that receive $600 or more of interest in a year send a Form 1098-VLI with the interest paid and the car’s VIN, by January 31. If your lender doesn’t send one, use your loan statements.
This article summarizes IRS Tax Tip 2026-79 and the final regulations published in Internal Revenue Bulletin 2026-39. It is not tax advice: check your situation with a tax professional or the IRS before claiming the deduction. Offers and rates can change at any time.