The first stop in our guide to buying a car with $0 down in 2026 is the one you see on TV: automakers advertising 0% APR with no money down. These offers are real, and in November 2026 there are a lot of them. Incentive trackers counted 44 national 0% programs at the start of the month.
Here is the part the ad leaves out. According to Edmunds, only 1.2% of new-car buyers actually financed at 0% in the second quarter of 2026. The offers exist. Most people who walk in for one leave with something else.
What is being advertised in November 2026
These are national offers from the automakers’ own finance companies, as published in their fine print for this month. Most end on November 30.
| Brand | Offer | Fine print |
| Hyundai | 0% APR for 60 months on 2026 Tucson and Santa Fe; “no down payment required” | Well-qualified buyers, Hyundai Motor Finance; ends Nov 30 |
| Nissan | 0% for 60 months on 2026 Rogue, Murano, Pathfinder; first payment in 90 days | NMAC approval, “not all buyers qualify”; ends Nov 30 |
| Subaru | 0% for 72 months on 2026 Trailseeker and Uncharted, with $1,500 cash | Approved credit; ends Nov 29–30 |
| Ford | 0% for 60 months on 2026 Explorer and F-150; 90-day deferred payment programs | Ford Credit approval; deferral deliveries by Jan 4, 2027 |
| Mazda | 0% on 2026 CX-90 and CX-70 | Mazda Financial Services; ends Nov 30 |
Kia and Toyota run 0% programs too, mostly on electric models: up to 72 months on the 2026 Niro EV and the 2026 bZ Woodland, the latter “for only very well qualified customers”. Offers vary by region, so confirm the exact terms with a dealer near you.
The line that decides who gets 0%
Every one of these offers has the same phrase: “for well-qualified buyers”. It means the top credit tier of the automaker’s lender. The lenders don’t publish the cutoff, but it sits inside what Experian calls prime and super prime credit, and buyers below it get “higher finance rates”, in the words of Hyundai’s fine print.
That is the gap between the ad and the showroom. You come in for 0%, the lender places you one tier down, and the dealer offers a standard loan at 7% or more. Most people sign it, because they have already picked the car.
Check this before you go
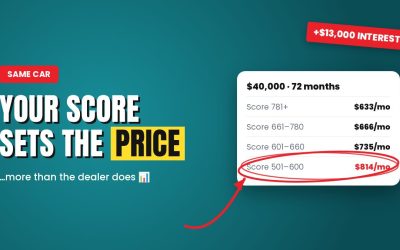
- Know your score. Free from your bank or card issuer. With a score below roughly 700, treat 0% as a bonus, not a plan.
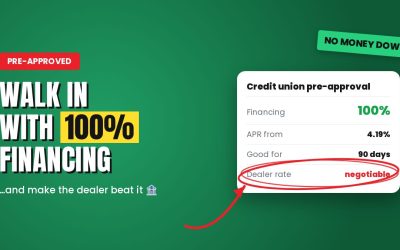
- Get a pre-approval of your own. A credit union or bank pre-approval gives you a rate to compare. If the dealer can’t beat it, you don’t lose anything. We explain how in our article on credit unions that finance 100% of a car.
- Ask whether 0% replaces the cash rebate. Many brands make you choose between 0% and a cash discount. On a cheap model, the cash plus a normal loan can come out ahead.
- Check the term. 0% for 36 months means a much bigger payment than 0% for 72.
“No payments for 90 days”
Nissan, Ford and some Subaru dealers advertise a first payment three months after you sign. Read how each one words it. Nissan says the deferral “does not increase monthly payment or total amount financed”. On GM’s October program, the fine print said finance charges accrue from the day you finance. A Subaru dealer reminds buyers that deferred payments are “not waived or forgiven”.
A deferral is useful if you need the cash this month. It does not make the car cheaper.
Is it worth it?
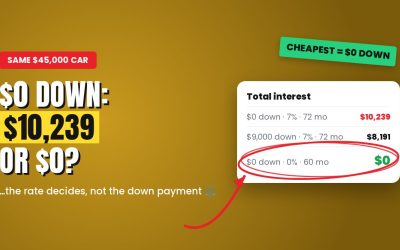
If you have strong credit, a 0% offer with no money down is the cheapest way to finance a new car in 2026: on a $45,000 car over 60 months, it saves more than $8,000 in interest compared with the 7% average loan. If your credit is fair, skip the ad and look at what your score really gets you in our article on $0 down with fair or bad credit.
Offers, rates and rules are those published by each automaker, lender or agency as of November 2026 and can change at any time; manufacturer offers usually end with the month and vary by region. Approval and your rate depend on your credit. This article is for information only and is not financial or tax advice.