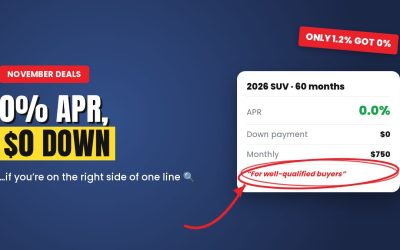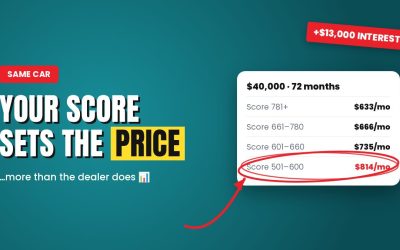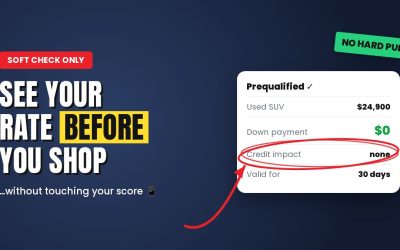
The most reliable path in our guide to buying a car with $0 down in 2026 isn’t a showroom offer. It’s a credit union, because several of them lend the full price of the car and publish rates below the national average.
Who lends 100% or more
| Lender | How much | Rates and who can join |
| Navy Federal | “100% financing available” | New from 4.19% APR (rates as of Nov 5, 2026); military, veterans, DoD and their families |
| PenFed | Up to 125% in the continental US, per PenFed | Low starting rates; open to anyone who opens an account |
| Local credit unions | Many finance 100% on newer cars; some up to 125% | Usually by where you live or work |
Navy Federal’s 4.19% is its best rate, for terms up to 36 months and excellent credit. Longer terms cost more: 4.89% up to 72 months, according to its rate page. Even so, the national average for a new-car loan was 7.0% in the third quarter of 2026, according to Edmunds.
Why a pre-approval saves you money at the dealer
When a dealer arranges your loan, the lender gives the dealer a “buy rate”. The dealer can add a margin on top and keep part of the extra interest. The Consumer Financial Protection Bureau says it plainly: the rate is negotiable, and you don’t have to finance through the dealer.
A pre-approval in your pocket changes the conversation. You can say: “My credit union approved me at this rate. Can you beat it?” If the dealer can, you take the dealer’s loan. If not, you use yours.
The catch with 125%
Financing more than the price sounds like a gift, but the extra 25% usually pays for taxes, fees, warranties or the balance of your old loan. A new car loses around 20% of its value in the first year, according to Experian. Borrow 125% and you will owe much more than the car is worth for years.
That’s the most common way people end up “underwater”, and it’s what makes the next car harder to buy. We explain how to avoid it in using your trade-in as a down payment.
How to do it
- Check if you can join a credit union through your job, your city or a family member in the military.
- Apply for pre-approval before you shop. Navy Federal’s pre-approvals are good for 90 days.
- Negotiate the price of the car first, and only then talk about financing.
- Take the pre-approval to the dealer and ask them to beat it.
Offers, rates and rules are those published by each automaker, lender or agency as of November 2026 and can change at any time; manufacturer offers usually end with the month and vary by region. Approval and your rate depend on your credit. This article is for information only and is not financial or tax advice.