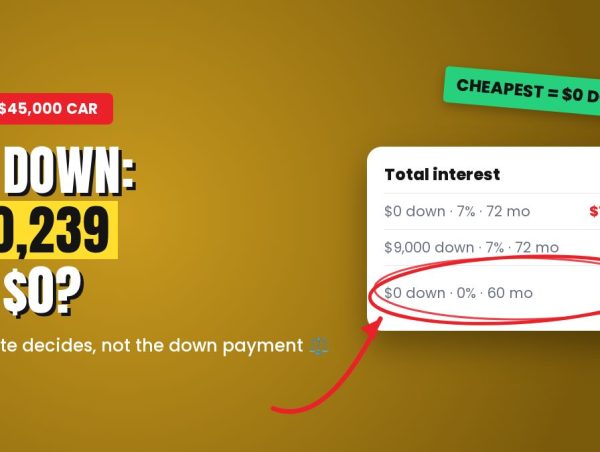
Every option in our guide to buying a car with $0 down in 2026 comes down to the same trade: money today or money later. Here is how big that trade really is, with the same car and the market’s average rate.
The same $45,000 car, four ways
We used $45,000, close to what the average new-car buyer financed in 2026, and 7.0% APR, the average new-car rate in the third quarter of 2026, according to Edmunds.
| How you pay | Monthly | Total interest |
| $0 down, 72 months | $767 | $10,239 |
| $0 down, 60 months | $891 | $8,463 |
| 20% down ($9,000), 72 months | $614 | $8,191 |
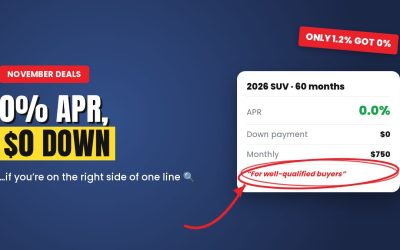
| $0 down at 0% APR, 60 months | $750 | $0 |
Two things stand out. First, a bigger down payment saves less interest than most people think: $9,000 down saves about $2,000. Second, the cheapest line in the table is a $0-down deal. Zero down isn’t the problem. A high rate on a long loan is.
After one year: what you owe vs. what it’s worth
A new car loses about 20% of its value in the first year, according to Experian. So the $45,000 car is worth about $36,000 after twelve months.
| How you paid | You still owe | Equity |
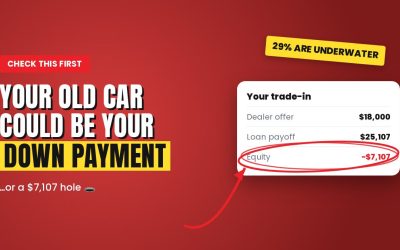
| $0 down, 72 months | $38,745 | About $2,700 underwater |
| 20% down, 72 months | $30,996 | About $5,000 positive |
That gap is what matters if the car is totaled or you need to sell. It’s why GAP insurance matters with $0 down, and why the next trade-in gets harder. We explain both in using your trade-in as the down payment.
Where the tax deduction fits
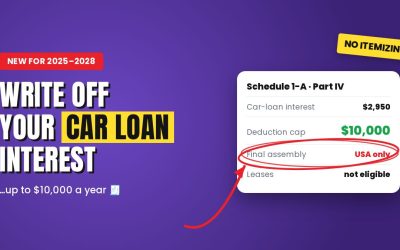
If the car was assembled in the US and your income is under $100,000, the new car-loan interest deduction gives part of the interest back. In the $0-down, 72-month example, first-year interest is about $2,950, worth roughly $650 in the 22% bracket. It helps, but it doesn’t change the ranking.
So which one?
- Strong credit: look for a 0% offer first. It beats any down payment. See this month’s 0% deals.
- Fair credit: a smaller loan and a shorter term matter more than the brand. Get a credit union pre-approval to compare.
- You need the lowest payment: a lease with $0 due can cost about the same in total, as we show in “$0 due at signing” leases.
- Your budget is tight: the old 20/4/10 rule (20% down, 4 years, payments under 10% of income) is hard to follow at today’s prices, but the idea behind it still works: keep the term short and the payment small.
Payments calculated by us with standard loan amortization, before taxes, fees and insurance. Average rates: Edmunds (Q3 2026); depreciation estimate: Experian. Your rate depends on your credit. This article is for information only and is not financial advice.