For many buyers, the realistic path in our guide to buying a car with $0 down in 2026 is a used car. The average new car sold for $50,562 in September 2026, according to Kelley Blue Book. The average used-car loan was about $30,700, according to Edmunds.
The best tool for used cars is free and doesn’t touch your credit score: prequalification with a soft credit check.
Where you can prequalify
| Where | Soft check? | What they ask |
| Capital One Auto Navigator | Yes | At least $1,500 a month in income; car up to about 10 years and 120,000 miles; financing from $4,000 |
| CarMax | Yes | No minimum credit score; down payment not required for most customers |
| Carvana | Yes | Terms shown for each car; only for cars bought from Carvana |
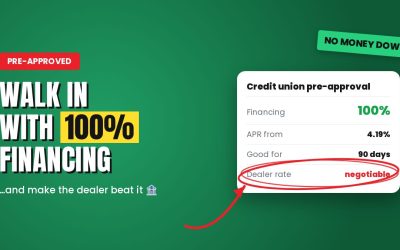
Capital One’s prequalification is valid for 30 days at participating dealers, and the hard credit check only happens when you finalize at the dealer. CarMax says more than 95% of applicants get prequalified, and its terms are also valid for 30 days.
$0 down is possible, but look at the rate
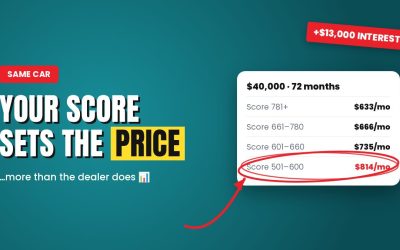
CarMax says a down payment is not required for most customers, but it recommends one. Used-car rates are higher than new ones: Experian’s Q2 2026 averages go from 6.29% for the best credit to 21.62% for the lowest tier. With no money down and a high rate, a used car can lose value faster than you pay it down.
The order that protects your score
- Prequalify in two or three places with soft checks, in the same week.
- Pick the car that fits the payment you were offered, not the other way around.
- Ask a credit union to beat the best offer. Navy Federal publishes used-car rates from 5.09% for members.
- Do the final application. If you shop for rates within a short window, credit scoring models usually count several auto inquiries as one.
Before you sign
- Get a vehicle history report and, if possible, an inspection by an independent mechanic.
- Ask for the out-the-door price, with taxes and fees.
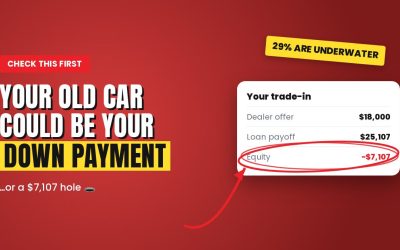
- Say no to add-ons you didn’t ask for. You can buy GAP from your insurer for less, as we explain in our article on trade-ins and negative equity.
Offers, rates and rules are those published by each automaker, lender or agency as of November 2026 and can change at any time; manufacturer offers usually end with the month and vary by region. Approval and your rate depend on your credit. This article is for information only and is not financial or tax advice.