Every option in our guide to buying a car with $0 down in 2026 depends on one number: your credit score. It decides whether you get 0%, a normal loan or no approval at all, and the difference is bigger than most people expect.
The same loan at each credit tier
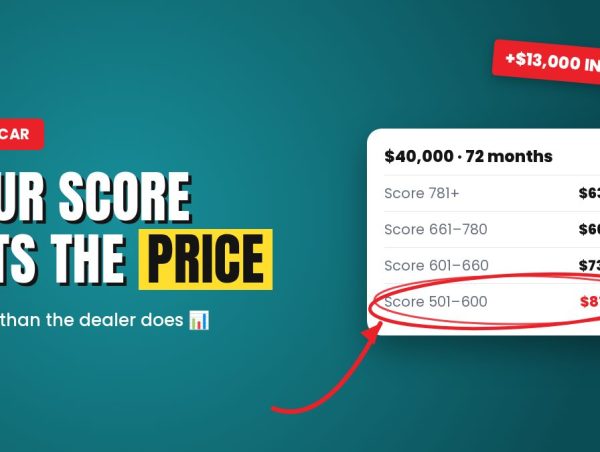
These are Experian’s average new-car APRs for the second quarter of 2026, applied to the same $40,000 loan over 72 months:
| Credit tier | Avg. APR | Monthly | Total interest |
| Super prime (781–850) | 4.41% | $633 | $5,598 |
| Prime (661–780) | 6.15% | $666 | $7,934 |
| Near prime (601–660) | 9.71% | $735 | $12,934 |
| Subprime (501–600) | 13.52% | $814 | $18,607 |
| Deep subprime (300–500) | 16.11% | $870 | $22,647 |
The car is the same. The subprime buyer pays about $13,000 more for it. That’s why raising your score by one tier before buying can be worth more than any dealer discount.
Can you get $0 down with fair credit?
Often, yes, but at a cost. Lenders look at more than your score: they check how much of your income the payment takes. Many subprime lenders keep the car payment at around 15–20% of your gross monthly income, and your total debts below 45–50%. With no down payment, the loan is bigger, so it’s harder to fit inside that limit.
Putting even $1,000 or $2,000 down can be the difference between an approval and a denial.
A co-signer: what it really means
A co-signer with better credit can get you approved or lower your rate. But the CFPB is clear about the risk for them: the co-signer owes the whole debt, has no right to the car, can be pursued by the lender without the lender first going after you, and every late payment shows on both credit reports.
Buy-here-pay-here: the last stop
“No credit check” dealers finance the car themselves. A Federal Reserve study published in May 2026 found an average rate of 25.39% for subprime borrowers at these dealers, against 14.60% at traditional lenders, and their loans were 16 times more likely to be in repossession. Many install devices that can stop the car from starting if a payment is late, and some report only your missed payments to the credit bureaus.
What to do instead
- Check your credit reports for free at AnnualCreditReport.com and dispute errors.
- Prequalify with soft-pull lenders first: it doesn’t affect your score. We explain how in buying a used car with no money down.
- Try a credit union: some approve members with fair credit at better rates than dealers.
- Consider a cheaper used car now and refinancing in a year, once your score improves.
Offers, rates and rules are those published by each automaker, lender or agency as of November 2026 and can change at any time; manufacturer offers usually end with the month and vary by region. Approval and your rate depend on your credit. This article is for information only and is not financial or tax advice.